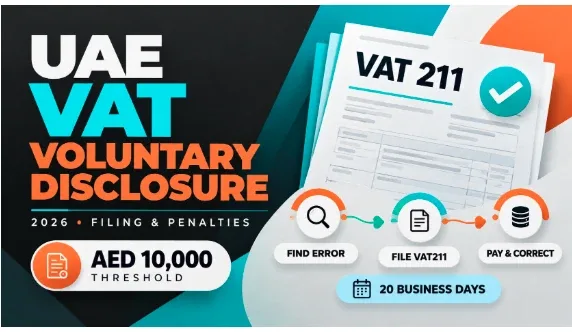
UAE VAT Voluntary Disclosure : Filing & Penalties Quick Answer: VAT voluntary disclosure allows UAE businesses to correct errors in previously submitted VAT returns, assessments or refund applications. If an error understates payable VAT by more than AED 10,000, businesses generally must submit Form VAT211 within 20 business days of discovering it. Penalties may apply.
Businesses sometimes discover missing sales invoices, incorrect VAT calculations or ineligible input VAT claims after filing their returns.
The Federal Tax Authority (FTA) provides a voluntary disclosure process to correct qualifying mistakes. Understanding when to disclose, how much tax is affected and what penalties apply can help businesses avoid further compliance problems.
1. What Is VAT Voluntary Disclosure?
VAT voluntary disclosure is a formal correction submitted to the FTA when a business identifies an error or omission in an earlier tax declaration.
It can relate to:
Previously filed VAT returns.
FTA tax assessments.
VAT refund applications.
Incorrect output VAT.
Overclaimed input VAT.
Other errors requiring disclosure under the Tax Procedures Law.
The process uses Form VAT211, submitted through EmaraTax.
Voluntary disclosure is different from filing an ordinary VAT201 return.
2. When Is Voluntary Disclosure Mandatory?
The correction method depends on the nature and value of the error.
The AED 10,000 threshold refers to the tax difference, not the value of the underlying sales or purchases.
For example, omitting AED 300,000 of standard-rated sales could create AED 15,000 of additional VAT, generally requiring disclosure.
3. What Is the VAT Voluntary Disclosure Deadline?
Where a qualifying error understates payable VAT by more than AED 10,000, the business generally must submit the voluntary disclosure within 20 business days from discovering the error.
For smaller qualifying errors, correction through the applicable VAT return is ordinarily permitted.
Businesses should record when the mistake was discovered and preserve supporting evidence.
Delaying the correction can increase financial exposure because penalties may accumulate over time.
4. How Do You File Form VAT211?
Businesses can submit voluntary disclosures electronically through the FTA's EmaraTax platform.
The general process is:
Log in to EmaraTax.
Open the relevant taxable person profile.
Select the VAT account.
Access the voluntary disclosure service.
Select the original return or assessment.
Enter the corrected figures.
Explain the reason for the adjustment.
Upload the relevant supporting documents.
Review and submit Form VAT211.
Keep the acknowledgement and review the resulting tax and penalty liabilities.
5. What Documents Should Be Prepared?
Before submitting the correction, reconcile the original VAT return against the business's accounting records.
Important documents include sales invoices, purchase invoices, credit notes, general ledger extracts, import records and VAT calculation schedules.
Businesses should prepare a reconciliation clearly identifying the originally reported amount, corrected amount and resulting tax difference.
For example:
Since the additional VAT exceeds AED 10,000, voluntary disclosure is generally required.
6. What Are the VAT Voluntary Disclosure Penalties in 2026?
The UAE amended its administrative penalty framework through Cabinet Decision No. 129 of 2025, effective 14 April 2026.
The 1% monthly voluntary disclosure penalty generally runs from the day after the original return due date until disclosure submission.
Additional tax and late-payment consequences may apply. Businesses should calculate the actual exposure using the relevant assessment dates and FTA rules.
7. When Must Additional VAT Be Paid?
Where voluntary disclosure results in additional payable tax, businesses should settle the liability within the applicable payment deadline.
Under the amended penalty framework, the payment deadline for a voluntary disclosure is generally 20 business days after submission.
Failure to settle the additional tax within the required period can trigger late-payment penalties.
Early reconciliation and disclosure can help reduce unnecessary delays and penalties.
8. How Can Vinimay Help Businesses Identify VAT Errors?
Accurate sales and purchase records help identify discrepancies before and after VAT return filing.
Vinimay offers general invoice management, purchase recording, customer and vendor ledgers, payment tracking and financial reporting.
These features can help businesses organise transactions, investigate missing entries and prepare supporting information for their accountants.
However, Vinimay's UAE-specific VAT211 filing, voluntary disclosure calculations, FTA integration and regulatory compliance capabilities have not been independently verified.
Businesses should confirm the required functionality before relying on software for statutory corrections.
Frequently Asked Questions
Related Topics
Published by admin
Our editorial and compliance specialists create practical guides, tax calculation rules, and operational strategies to empower Indian small business owners and accountants.