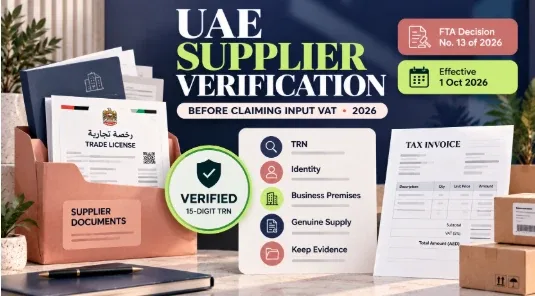
UAE Supplier Verification Before Claiming Input VAT Quick Answer: Before claiming input VAT in the UAE, businesses must verify their suppliers, check VAT registration numbers, obtain valid tax invoices and confirm that purchases are genuine. From 1 October 2026, FTA Decision No. 13 of 2026 introduces additional supplier and transaction verification requirements.
Recovering input VAT helps UAE businesses reduce their net tax liability. However, having a supplier invoice is not always sufficient.
The Federal Tax Authority (FTA) requires businesses to ensure that VAT is correctly charged and that transactions are genuine. The new 2026 verification rules make supplier due diligence especially important for finance and procurement teams.
1. Why Is Supplier Verification Important for Input VAT?
Input VAT is the tax a business pays on eligible purchases and expenses.
For example, a UAE trading company purchases goods worth AED 20,000 plus AED 1,000 VAT. The company may recover the AED 1,000 if the relevant conditions are satisfied.
However, input VAT recovery can be challenged when invoices are invalid, purchases are not genuine or transactions are connected with tax evasion.
Under Article 54(bis) of the UAE VAT Law, a business may be denied input VAT recovery if it knew, or should have known, that a transaction was connected to tax evasion.
2. What Changed Under FTA Decision No. 13 of 2026?
Effective 1 October 2026, FTA Decision No. 13 introduced specific verification procedures before deducting input VAT.
Businesses must assess supplier identity, business premises, relevant risk indicators and the commercial validity of supplies.
The rules also require businesses to document their checks and maintain a written verification policy.
These requirements supplement existing VAT invoice and recovery conditions.
3. How Do You Verify a Supplier's TRN?
A supplier charging UAE VAT should have a valid Tax Registration Number (TRN).
Businesses can verify the 15-digit TRN through the official FTA website.
Check that the supplier's identity is consistent with the invoice and other business documentation.
Also review whether the invoice contains prescribed particulars, including supplier details, invoice date, description, VAT amount and total value.
A valid TRN alone does not establish that a transaction is genuine or that input VAT is recoverable.
4. What Documents Are Needed for Supplier Verification?
The required checks depend on whether the supplier is an individual or a legal entity.
For a company, verification may include:
Trade licence or incorporation records.
Identification of its authorised representative.
Confirmation of its actual business premises.
Relevant supplier risk assessments.
Evidence supporting the commercial transaction.
For an individual supplier, the rules include obtaining valid identification and meeting the supplier in person or virtually before the supply.
Supplier verification generally applies when first dealing with a supplier or when the supplier has not been verified within the preceding 12 months.
5. What Transaction Checks Must Businesses Perform?
Businesses must assess the validity and integrity of the supplies received.
For example, when purchasing stock, a company should confirm that the supplier can genuinely supply the goods.
Relevant checks include the commercial purpose, goods' origin and ownership, pricing and payment arrangements.
A practical comparison is:
Unusual prices, unexplained intermediaries or suspicious payment arrangements should be investigated.
6. Are There Exceptions or Higher-Value Checks?
FTA Decision No. 13 provides a limited exception for taxable supplies valued below AED 10,000 excluding VAT.
However, this exception does not apply if supplies from that supplier exceed AED 100,000 over the previous 12 months or are expected to exceed that amount during the next 12 months.
Enhanced requirements also apply in certain higher-value supplier relationships, including additional bank-account confirmation where relevant supplies exceed AED 375,000 over the applicable period.
Businesses should assess these thresholds carefully rather than treating every small invoice as automatically exempt.
7. What Happens If Verification Is Not Completed?
Failure to perform and document the required checks may affect the business's ability to defend input VAT recovery where a supply is linked to tax evasion.
The FTA may deny the relevant input VAT deduction and assess additional tax. Applicable penalties may also arise depending on the circumstances.
Businesses should maintain a written supplier verification policy identifying who performs, reviews and supervises the checks.
Verification evidence should be retained with the relevant accounting and purchasing documentation.
8. How Can Vinimay Help With Supplier Records?
Organised supplier and purchase information makes verification easier to manage.
Vinimay provides general features for maintaining vendor records, purchase invoices, payment transactions, ledgers and financial reports.
These features can help businesses identify suppliers, review transactions and organise supporting information for an accountant.
However, Vinimay's automated UAE TRN verification, FTA Decision No. 13 due diligence checks, input VAT recovery compliance and FTA integration have not been independently verified.
Businesses should implement the required verification and approval procedures separately unless the software's relevant functionality has been confirmed.
Frequently Asked Questions
Related Topics
Published by admin
Our editorial and compliance specialists create practical guides, tax calculation rules, and operational strategies to empower Indian small business owners and accountants.