What Is a Permanent Establishment, and How Are Foreign Companies Taxed in the UAE?
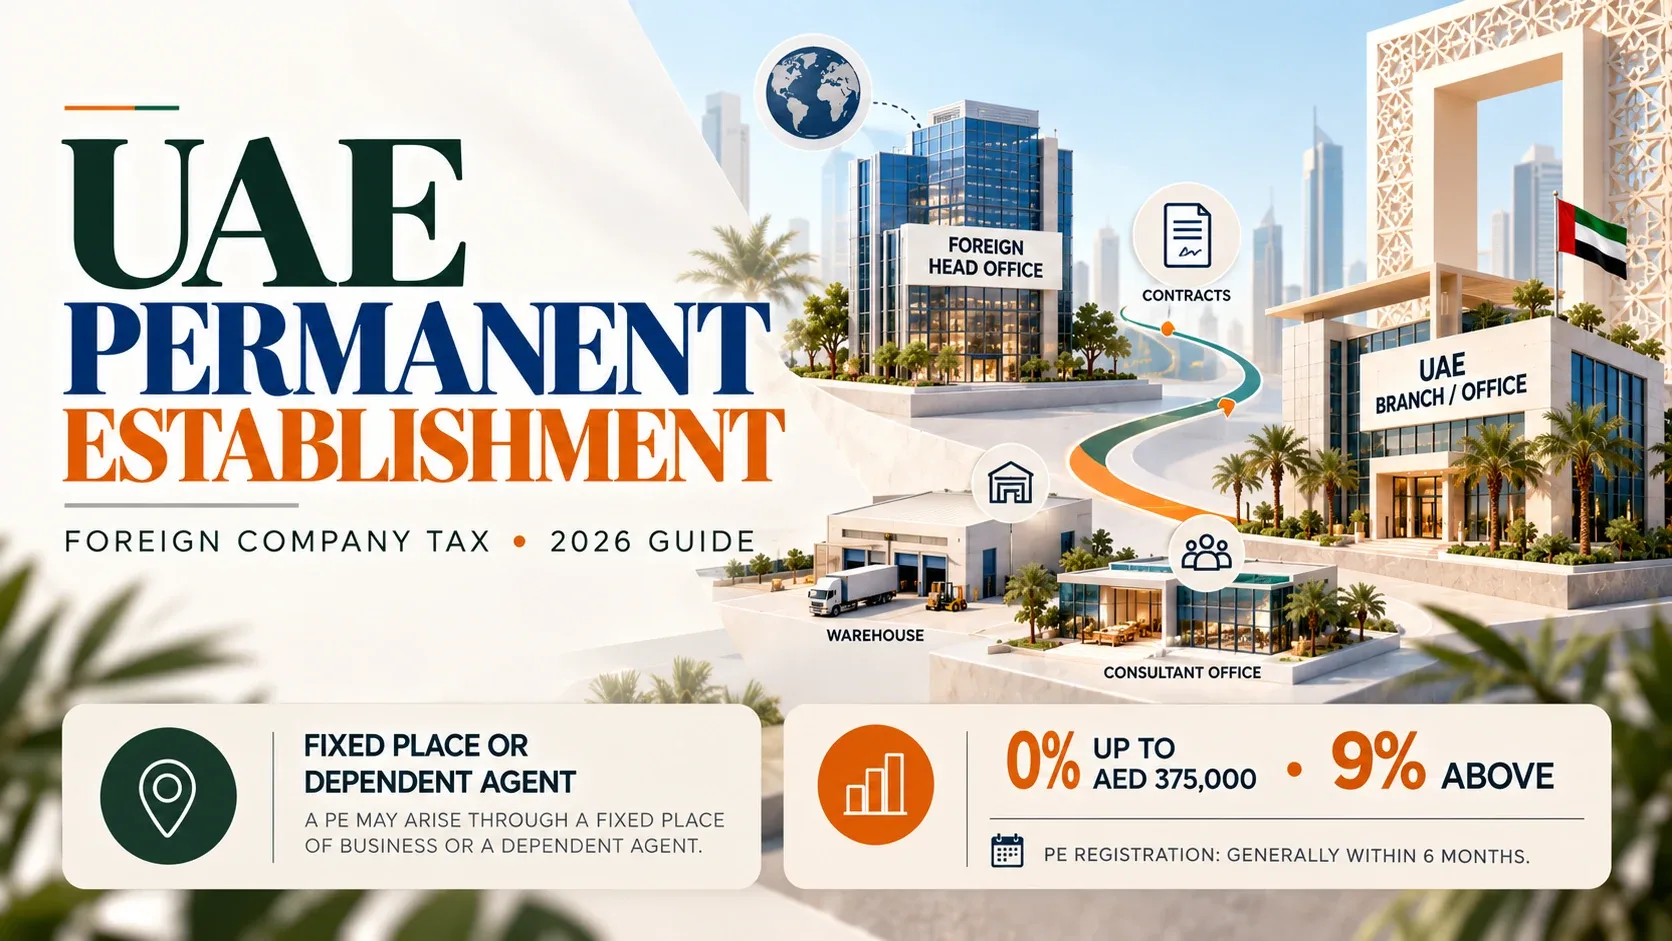
Quick Answer: A Permanent Establishment (PE) is generally a fixed business location or dependent agent through which a foreign company conducts business in the UAE. Foreign companies with a UAE PE may owe Corporate Tax on attributable profits. The standard rates are 0% up to AED 375,000 and 9% above that amount.
Foreign businesses frequently serve UAE customers through offices, branches, employees and local representatives. However, not every business relationship creates a taxable presence.
Understanding the Permanent Establishment rules helps overseas companies determine when UAE Corporate Tax registration and filing become necessary.
What Is a Permanent Establishment?
A permanent establishment is a business presence that may make a non-resident company liable for UAE corporate tax.
Under Article 14 of the Corporate Tax Law, a PE can arise through a fixed business location or a person habitually conducting business on behalf of the foreign company.
For example, a UK company operating a permanent Dubai office to deliver consulting services may have a UAE PE.
The exact outcome depends on its activities, operating arrangements, and applicable tax treaties.
What Activities Can Create a UAE PE?
Common examples include:
A branch or office conducting business.
A factory or workshop.
A place of management.
A qualifying construction site lasting more than six months.
A dependent agent habitually concluding contracts.
A fixed place must generally have sufficient permanence and be used for carrying on the foreign company's business.
The mere existence of a customer, website or UAE mailing address does not automatically establish a PE.
What Is a Dependent Agent PE?
A dependent agent PE may arise where a person in the UAE habitually concludes contracts for the foreign business or negotiates contracts that are routinely concluded without material changes.
For example, a local representative regularly negotiating and finalizing commercial agreements for an overseas supplier may create a PE.
An independent agent conducting business in the ordinary course of their own activities generally does not create a PE, subject to the independence conditions.
Which Activities May Be Excluded?
Certain activities of a preparatory or auxiliary nature generally do not create a fixed-place PE when the statutory conditions are satisfied.
Examples may include storage, displaying goods, or collecting market information.
However, exclusions cannot be used to artificially split an integrated business into smaller activities.
Tax treaty provisions may also change the applicable PE tests.
How Are Foreign Companies Taxed?
Tax treatment depends on the foreign company's UAE presence and income.
A foreign company's UAE ownership or customer relationships do not alone determine its Corporate Tax liability.
How Is PE Corporate Tax Calculated?
The taxable profits attributable to a PE are determined using the relevant UAE Corporate Tax rules.
Consider a simplified example:
This example assumes no other tax adjustments or special rules.
Profits must be attributed to the PE using appropriate transfer pricing and arm's length principles.
What Are the Registration and Filing Deadlines?
A foreign juridical person becoming a non-resident taxpayer because of a UAE PE on or after 1 March 2024 generally must apply for corporate tax registration within six months of the PE coming into existence.
A foreign company establishing a qualifying immovable-property nexus on or after that date generally has three months to register.
Earlier-established PEs and nexuses had transitional deadlines.
Corporate Tax returns and payments are generally due within nine months of the relevant tax period ending.
Businesses can register and file through the FTA's EmaraTax platform.
How Can Vinimay Help With PE Accounting Records?
Foreign companies with UAE operations need accurate records of local revenue, expenses and transactions.
Vinimay provides general invoicing, purchase recording, customer and supplier ledgers, expense tracking and financial reporting features.
These functions can help organise UAE transaction information for accountants reviewing PE profits.
However, Vinimay's UAE-specific PE determination, profit attribution, transfer pricing analysis, Corporate Tax computation and EmaraTax filing capabilities have not been independently verified.
Foreign companies should obtain professional advice before determining whether a PE exists.
Conclusion
A foreign company may become subject to UAE Corporate Tax if it operates through a Permanent Establishment (PE) in the UAE or is considered a UAE tax resident because it is effectively managed and controlled in the country. A PE may arise through a branch, office, factory, or a dependent agent who habitually conducts business on the company’s behalf. However, certain preparatory or auxiliary activities may be excluded, subject to applicable conditions. Foreign businesses should assess their activities, applicable tax treaties, registration obligations, and filing deadlines to maintain compliance.
To simplify daily accounting, businesses can use Vinimay’s free bilingual billing software to create invoices in English and Hindi, manage sales bills, and organise transaction records. This free invoice billing software supports systematic billing and record-keeping for tax preparation.
Frequently Asked Questions
Related Topics
Published by prachi kahar
Our editorial and compliance specialists create practical guides, tax calculation rules, and operational strategies to empower Indian small business owners and accountants.