Quick Answer: UAE Corporate Tax Voluntary Disclosure allows businesses to correct qualifying errors in previously submitted tax returns or assessments. Corporate Tax deregistration is required when a taxable person ceases business or otherwise stops being subject to tax. Both procedures are handled through the Federal Tax Authority's EmaraTax platform.
UAE businesses sometimes discover mistakes after submitting corporate tax returns. Others may close, liquidate or merge their companies and need to cancel their corporate tax registration.
Although both procedures involve the Federal Tax Authority (FTA), they serve different purposes and have different requirements.
What Is Corporate Tax Voluntary Disclosure?
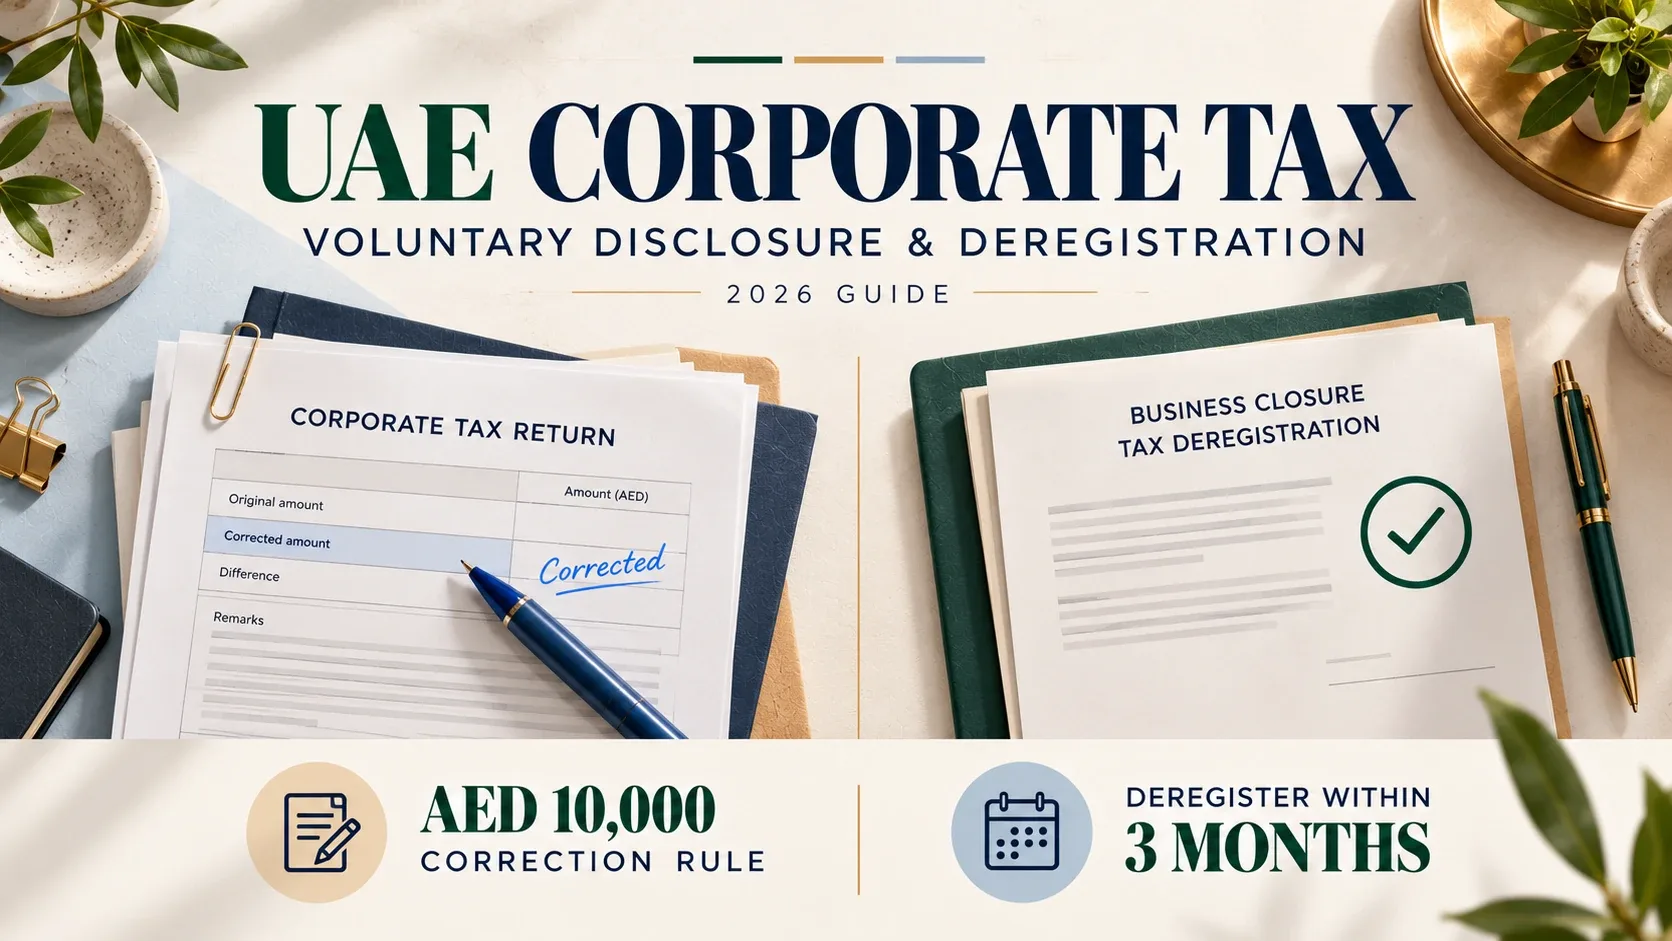
Voluntary disclosure is a formal procedure for correcting errors in previously filed Corporate Tax returns or tax assessments.
For example, a Dubai trading company may discover that it omitted sales income or claimed an expense that was not deductible.
The company must determine whether the mistake can be corrected in a subsequent return or requires a formal voluntary disclosure.
The procedure is governed by theUAE Tax Procedures Law and its Executive Regulation.
When Must Businesses Submit a Voluntary Disclosure?
The correction method depends on the error and its tax impact.
The AED 10,000 test relates to the Corporate Tax difference, not the amount of omitted revenue or expenses.
For example, if an incorrect deduction results in AED 13,500 of additional Corporate Tax, the business generally needs to disclose the error formally.
How Do You Submit Corporate Tax Voluntary Disclosure?
Businesses should first review the original return and calculate the correct taxable income.
The general process is:
- Log in to EmaraTax.
Open the relevant corporate tax account.
Locate the previously submitted return or assessment.
Access the applicable correction or voluntary disclosure service.
Enter the corrected figures.
Explain the nature and reason for the mistake.
Provide supporting documents where required.
Submit the disclosure and retain the acknowledgement.
Businesses should check the current EmaraTax workflow for Corporate Tax rather than using VAT211, which is the form associated with VAT voluntary disclosures.
Where applicable, additional tax and administrative penalties must also be addressed.
What Is Corporate Tax Deregistration?
Corporate Tax deregistration means formally cancelling a taxable person's Corporate Tax registration with the FTA.
It may be required because of:
Business closure.
Company liquidation or dissolution.
Merger with another company.
Sale or restructuring of a business.
Closure of a UAE permanent establishment.
Other qualifying changes in taxable status.
Deregistration is not automatic when a trade licence expires or a company stops issuing invoices.
The taxpayer must submit the appropriate application and obtain FTA approval.
What Is the Corporate Tax Deregistration Deadline?
FTA Decision No. 6 of 2023 establishes a general three-month application deadline.
For example, if a company permanently stops operating on 30 September 2026, it should generally apply by 30 December 2026.
A temporary shutdown or reduced turnover does not automatically justify deregistration.
Individuals operating multiple businesses should also assess whether all relevant business activities have ceased.
How Do You Apply for Deregistration Through EmaraTax?
The FTA provides a dedicated corporate tax deregistration service.
Follow these steps:
Log in to EmaraTax.
Open the Taxable Person Account.
Select the Corporate Tax section.
Choose the relevant deregistration action.
State the reason for deregistration.
Enter the cessation or other relevant date.
Upload supporting documentation.
Submit the application and monitor its status.
The application is free.
According to the FTA, a complete application is generally processed within 40 working days, although additional information may extend processing.
What Documents and Final Returns Are Required?
The FTA may require different documents depending on the reason for deregistration.
For a business closure, common documents include the licence cancellation certificate and financial statements up to the cancellation date.
Mergers may require the merger agreement, amended licence and related financial information.
Before approving deregistration, the FTA generally requires all relevant Corporate Tax returns to be filed and outstanding tax liabilities and penalties to be settled.
The final Corporate Tax return is not automatically due within 28 days. Under the ordinary Corporate Tax framework, returns are generally due within nine months after the relevant tax period ends, unless a special rule applies.
How Can Vinimay Help With Tax Corrections and Closure Records?
Accurate accounting records can make voluntary disclosures and business closure procedures easier to prepare.
Vinimay provides general features for maintaining sales invoices, purchases, expenses, customer and vendor ledgers, payment records and financial reports.
These functions can help businesses identify incorrect transactions, reconcile balances and organise information for accountants preparing final accounts.
However, Vinimay's UAE-specific Corporate Tax voluntary disclosure calculations, deregistration applications, penalty computations and direct EmaraTax integrations have not been independently verified.
Businesses should complete statutory submissions through the appropriate FTA procedures.
Frequently Asked Questions
Related Topics
Published by prachi kahar
Our editorial and compliance specialists create practical guides, tax calculation rules, and operational strategies to empower Indian small business owners and accountants.