What Is Qualifying Income?
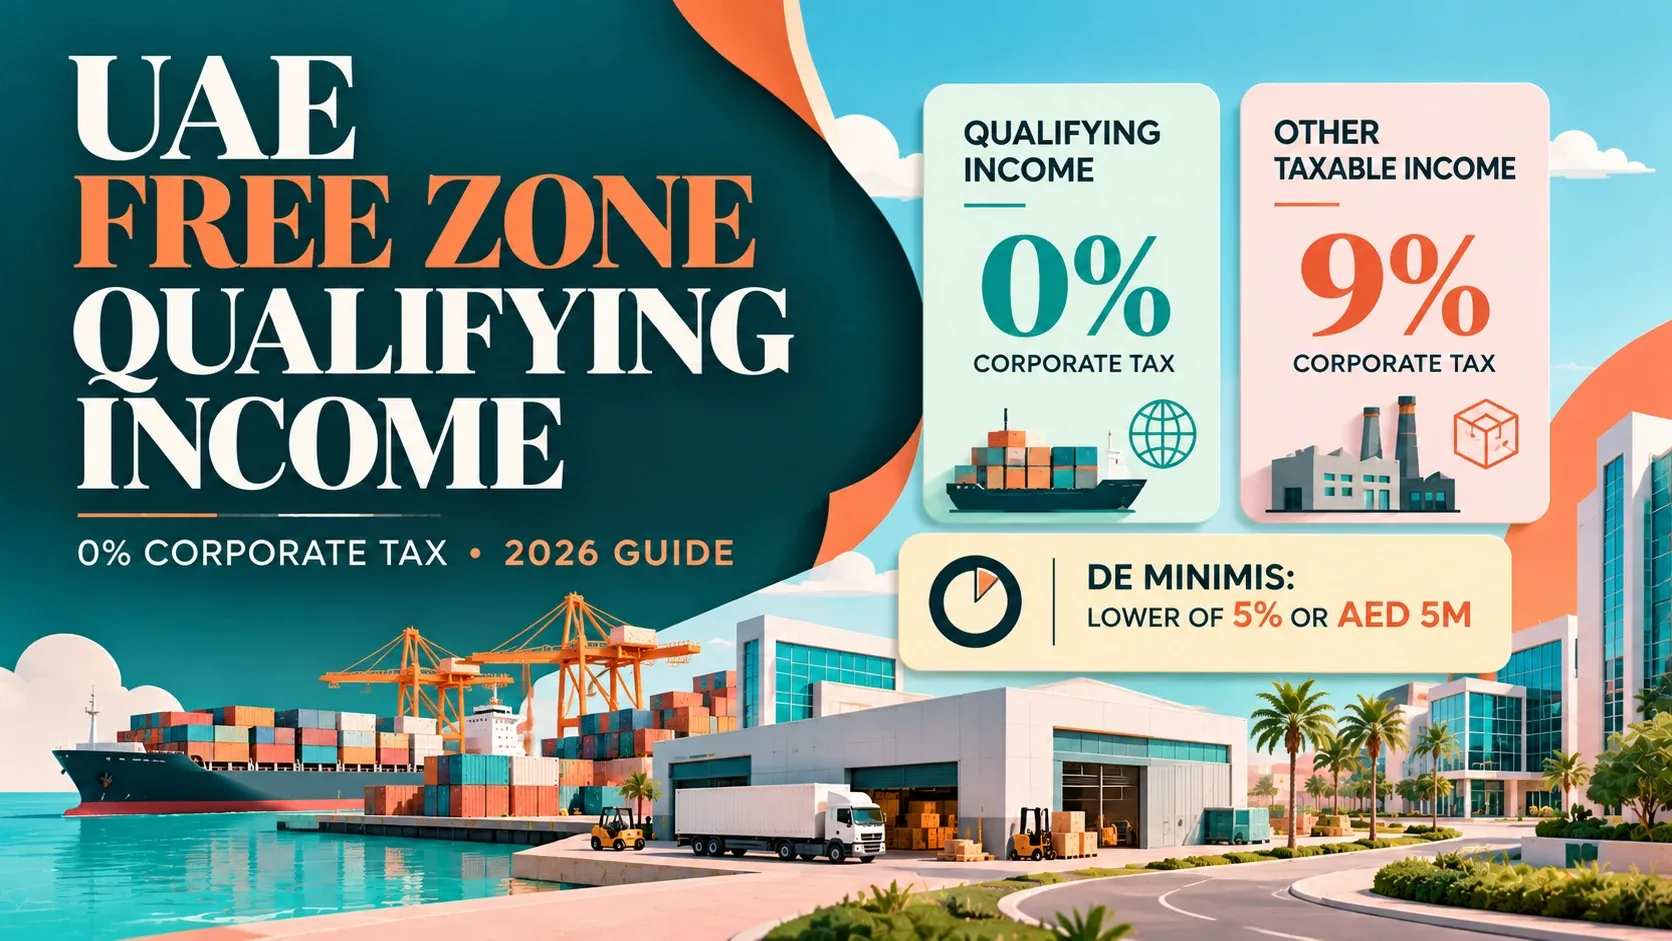
Quick Answer: Qualifying income is income that meets the UAE Corporate Tax conditions for preferential 0% taxation when earned by a Qualifying Free Zone Person (QFZP). It may arise from eligible transactions with other Free Zone businesses, specified qualifying activities and certain other permitted sources. Not every Free Zone company's income qualifies.
UAE Free Zones offer attractive business opportunities for trading companies, manufacturers, logistics providers and service businesses. However, operating in a Free Zone does not automatically make all profits tax-free.
Businesses must understand which income qualifies for the 0% Corporate Tax rate and which income is subject to ordinary taxation.
What Is Qualifying Income Under UAE Corporate Tax?
Qualifying Income is income eligible for the preferential 0% Corporate Tax rate under the UAE's Qualifying Free Zone Person framework.
Under Cabinet Decision No. 100 of 2023, qualifying income can generally arise from:
Eligible transactions with other Free Zone Persons.
Specified Qualifying Activities involving non-Free Zone customers.
Certain qualifying intellectual property income.
Other income within the permitted de minimis framework.
The applicable conditions and exclusions determine the actual treatment.
Who Can Benefit From the 0% Tax Rate?
A Free Zone business must qualify as a Qualifying Free Zone Person (QFZP).
Important conditions include maintaining adequate substance in the UAE, earning Qualifying Income, meeting transfer pricing requirements and preparing audited financial statements.
The business must also satisfy the de minimis requirements and other applicable conditions.
A QFZP does not receive the ordinary AED 375,000 zero-rate threshold on its non-qualifying taxable income.
Which Activities Can Generate Qualifying Income?
Ministerial Decision No. 229 of 2025 defines the current list of Qualifying Activities.
Examples include:
Manufacturing and processing goods.
Trading qualifying commodities.
Holding shares and securities for investment.
Logistics services.
Distribution of goods in or from a Designated Zone.
Headquarters services to related parties.
Treasury and financing services under specified conditions.
Certain shipping, aviation and regulated investment activities.
Important: Simply holding a general trading licence does not make every trading transaction a Qualifying Activity.
Are Sales to Mainland UAE Businesses Qualifying Income?
Sales to mainland customers do not automatically qualify for 0% Corporate Tax.
When a free zone company transacts with a non-free zone person,income generally qualifies only if it arises from a specified qualifying activity and is not an Excluded Activity.
For example, qualifying logistics services provided to a mainland company may be eligible.
Ordinary retail sales to mainland customers may not qualify.
The treatment depends on the business activity, transaction structure and applicable exclusions.
What Is the De Minimis Rule?
The de minimis rule allows a QFZP to earn a limited amount of non-qualifying revenue without automatically losing its preferential status.
The limit is the lower of:
5% of total relevant revenue or AED 5 million.
Example:
The AED 300,000 non-qualifying revenue is within the ceiling.
Certain categories are excluded from the de minimis calculation, so businesses must use the statutory revenue definitions rather than simply comparing every accounting income entry.
Which Income Is Generally Excluded?
Excluded Activities can include ordinary transactions with individuals, banking, certain insurance or finance activities and particular immovable-property transactions.
Some statutory exceptions apply.
For example, income from qualifying commercial property in a Free Zone may have different treatment from income involving residential property.
Businesses must also separately assess intellectual property income under the applicable special rules.
Exceeding the de minimis threshold can cause a company to lose QFZP status for the current tax period and the following four tax periods.
What Records Must Businesses Maintain?
Free Zone businesses must document the nature of their income and demonstrate their eligibility.
Useful records include customer contracts, invoices, supplier documentation, financial statements, transaction classifications and evidence of business activities.
QFZPs must prepare audited financial statements.
Corporate Tax supporting records generally must be retained for seven years after the relevant tax period.
Businesses should review revenue classifications throughout the year rather than waiting until their Corporate Tax return is due.
How Can Vinimay Help Track Qualifying Income?
Accurate transaction records make it easier to assess income from different customers and activities.
Vinimay provides general invoicing, sales recording, customer management, purchase tracking, ledgers and financial reporting features.
These functions can help businesses organise the transaction information required for accountant review.
However, Vinimay's UAE-specific QFZP classification, Qualifying Income calculations, de minimis monitoring and EmaraTax filing capabilities have not been independently verified.
Businesses should confirm their eligibility and income treatment with a qualified UAE Corporate Tax adviser.
Conclusion
Qualifying income in UAE Free Zones refers to income eligible for the 0% corporate tax rate, provided the business meets the requirements for qualifying as a free zone person. Under the 2026 rules, businesses must review their qualifying activities, customer transactions, substance requirements, transfer pricing compliance, and applicable exclusions. Non-qualifying taxable income may be subject to the
To simplify daily accounting, businesses can use Vinimay’s free bilingual billing software to create invoices in English and Hindi, manage sales bills and organize transaction records. This free invoice billing software supports systematic billing and record-keeping, helping businesses prepare for accounting and tax compliance.
Frequently Asked Questions
Related Topics
Published by prachi kahar
Our editorial and compliance specialists create practical guides, tax calculation rules, and operational strategies to empower Indian small business owners and accountants.