How Does the UAE 15% Top-Up Tax Work, Who Must Register, and by When?
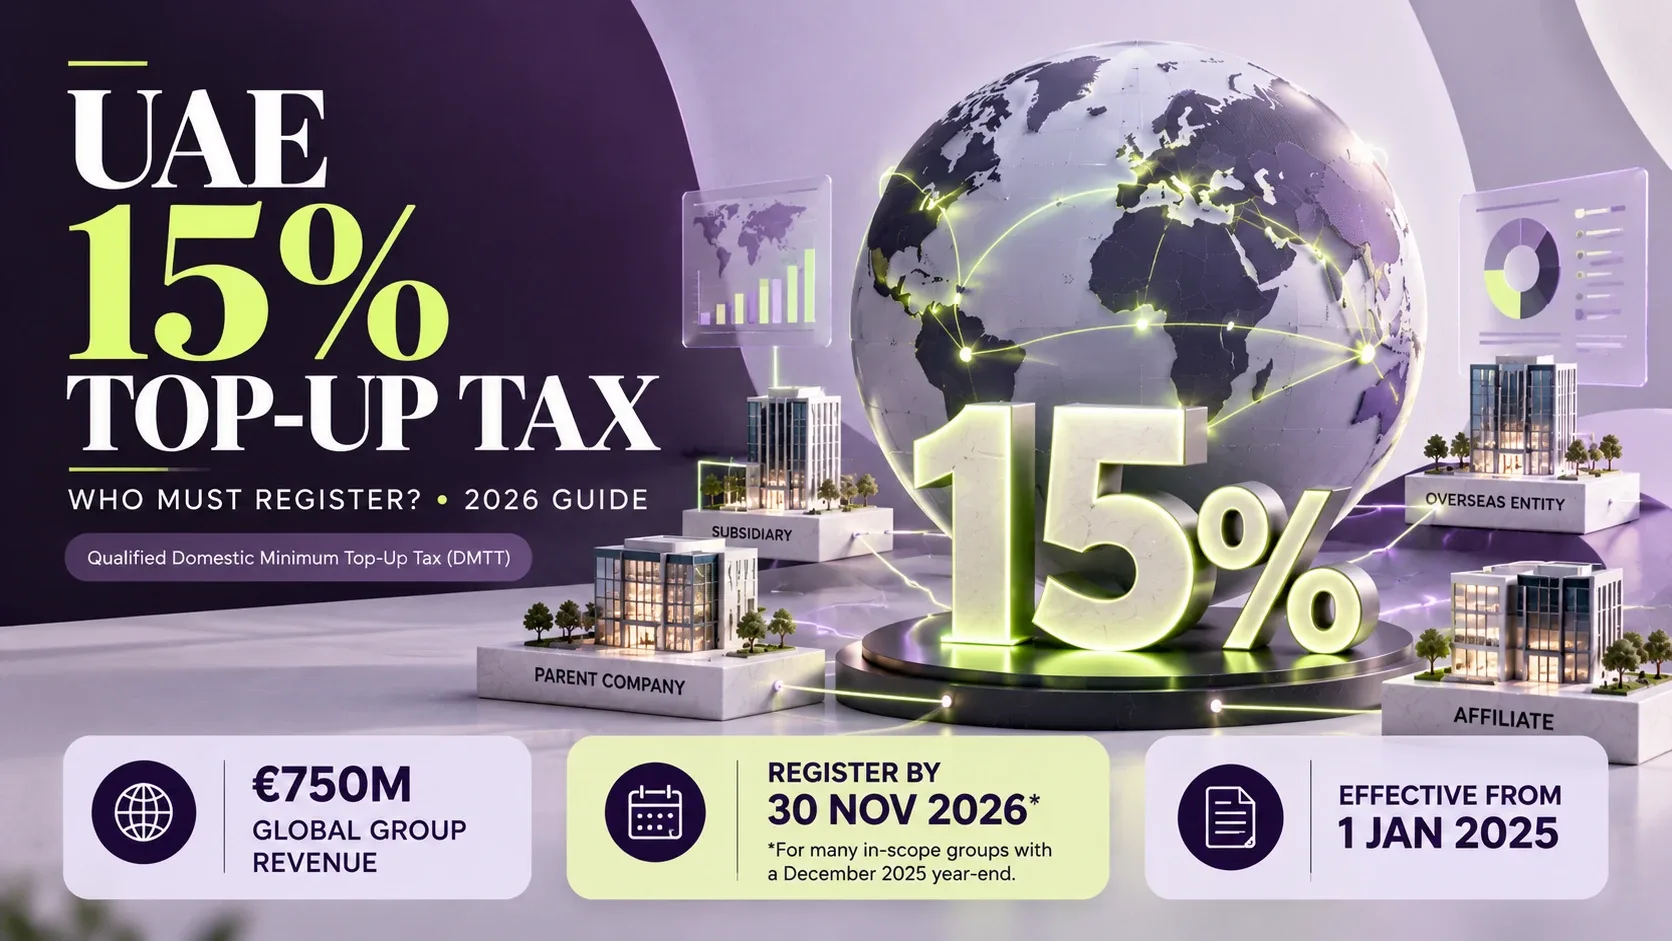
Quick Answer: The UAE's 15% Domestic Minimum Top-Up Tax applies to qualifying multinational enterprise groups with annual global revenue of at least €750 million in two of the preceding four financial years. It applies from financial years starting 1 January 2025. For many calendar-year groups, registration is due by 30 November 2026.
The UAE introduced the Domestic Minimum Top-Up Tax (DMTT), also known as the Qualified Domestic Minimum Top-Up Tax (QDMTT), under Cabinet Decision No. 142 of 2024.
It follows the OECD's Pillar Two framework, designed to ensure large multinational groups face a minimum effective tax rate of 15%.
Importantly, this is not a general increase in UAE corporate tax for all businesses.
What Is the UAE 15% Top-Up Tax?
The Top-Up Tax is an additional tax that may apply when an in-scope multinational group's effective tax rate on UAE profits falls below 15%.
The UAE introduced this system for financial years beginning on or after 1 January 2025.
Its purpose is to ensure that qualifying UAE profits are subject to the minimum tax under the applicable international framework.
Ordinary UAE Corporate Tax rules continue to apply separately.
Which Businesses Are Subject to Top-Up Tax?
The UAE DMTT generally covers UAE constituent entities of multinational enterprise groups meeting the following conditions:
The group operates in more than one jurisdiction.
Its consolidated annual global revenue reaches at least €750 million.
The revenue threshold is met in at least two of the four preceding financial years.
The relevant UAE entity falls within the legislation's scope.
The threshold is based on global group revenue, not the turnover of an individual UAE subsidiary.
Groups operating exclusively within the UAE are outside the DMTT framework.
Certain excluded entities, including qualifying investment entities, receive different treatment.
How Is the 15% Top-Up Tax Calculated?
Top-Up Tax calculations use the OECD GloBE framework, including adjusted income and covered taxes.
A simplified formula is:
Top-Up Percentage = 15% − Applicable Effective Tax Rate
Consider this illustration:
Before exclusions and other adjustments, the illustrative difference is AED 600,000.
Actual Top-Up Tax may be lower because the calculation can include substance-based income exclusions, deferred tax adjustments and safe-harbour provisions.
Businesses should not simply apply an additional 6% to their ordinary accounting profit.
When Must UAE Businesses Register for Top-Up Tax?
FTA Decision No. 12 of 2026 introduced specific registration timelines.
The general requirement is to register within seven months after the end of the first fiscal year in which the entity falls within scope.
A transitional deadline applies to entities whose first in-scope fiscal year ended before 30 April 2026.
For many multinational groups with a calendar financial year, 30 November 2026 is the key approaching registration deadline.
How Do Businesses Register?
In-scope entities should follow the FTA's registration guidance through EmaraTax.
The general preparation process involves:
Determine whether the multinational group exceeds the revenue threshold.
Identify UAE constituent entities, permanent establishments and relevant joint ventures.
Gather consolidated financial statements and ownership details.
Confirm whether exclusions or special provisions apply.
Access the applicable Top-Up Tax registration service.
Submit entity and group information.
Retain confirmation of registration.
The FTA published a dedicated Scope and Registration Guide in October 2026 to assist affected entities.
When Are Top-Up Tax Returns and Payments Due?
Registration, information reporting, and tax payment are separate obligations.
For a typical group with its first in-scope financial year ending 31 December 2025:
The Top-Up Tax return normally follows a 15-month deadline, extended to 18 months for the first applicable transition year.
The Pillar Two Information Return has separate reporting rules, including potential filing through a designated group entity.
Businesses should verify their actual obligations and dates based on the applicable legislation.
How Does a Top-Up Tax Affect Free Zone Companies?
A Free Zone entity is not automatically outside the Top-Up Tax regime.
Even where a qualifying free zone person benefits from 0% corporate tax on qualifying income, its multinational group may still fall within DMTT.
The outcome depends on group-wide eligibility, UAE jurisdictional calculations, applicable exclusions, and safe harbors.
Similarly, smaller UAE companies that are not part of a qualifying multinational group generally do not fall within the DMTT.
How Can Vinimay Help Businesses Prepare?
Top-Up Tax reporting requires reliable revenue, expense and accounting information.
Vinimay provides general invoicing, purchase records, customer and supplier ledgers, expense tracking and financial reporting features.
These functions can help businesses organise entity-level transaction data for finance teams and tax advisers.
However, Vinimay's Pillar Two GloBE calculations, DMTT registration, multinational consolidation, safe-harbour assessments and EmaraTax filing capabilities have not been independently verified.
Large multinational groups should use specialist tax expertise and appropriate consolidation systems for Top-Up Tax compliance.
Conclusion
The UAE’s 15% Top-Up Tax applies to eligible UAE entities that are part of multinational enterprise (MNE) groups with consolidated annual revenue of at least €750 million in at least two of the four preceding fiscal years. The rules apply to fiscal years beginning on or after 1 January 2025. For entities whose first in-scope fiscal year ended before 30 April 2026, the transitional registration deadline is 30 November 2026; otherwise, registration is generally due within seven months after the end of the first in-scope fiscal year. Businesses should review their eligibility and registration obligations with a qualified tax adviser.
To simplify daily accounting, businesses can use Vinimay’s free bilingual billing software to create invoices in English and Hindi, manage sales bills, and organise transaction records. This free invoice billing software supports systematic billing and record-keeping for tax preparation.
Frequently Asked Questions
Related Topics
Published by prachi kahar
Our editorial and compliance specialists create practical guides, tax calculation rules, and operational strategies to empower Indian small business owners and accountants.