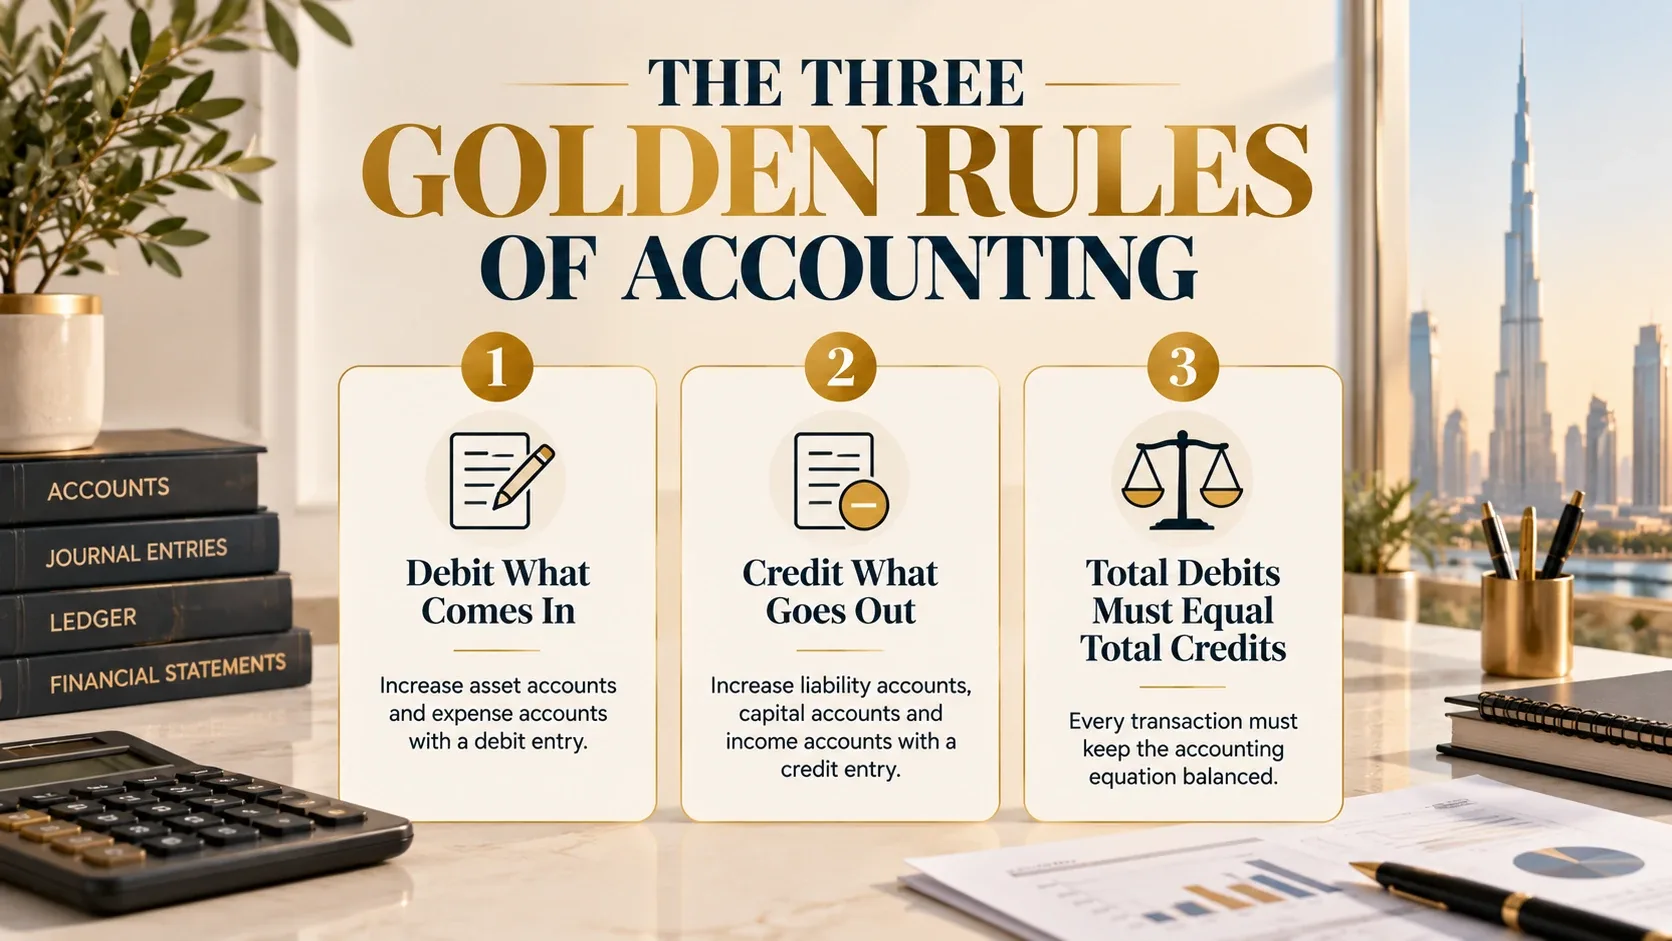
Quick Answer: The three golden rules of accounting are: (1) Debit the receiver, credit the giver for personal accounts; (2) Debit what comes in, credit what goes out for real accounts; and (3) Debit all expenses and losses, credit all incomes and gains for nominal accounts.
Understanding these rules is one of the easiest ways to learn bookkeeping.Whether you run a trading company, retail shop, consultancy, or manufacturing business in the UAE, these principles explain how financial transactions are recorded.
They form part of the traditional approach to double-entry bookkeeping.
1. What Are the Three Golden Rules of Accounting?
Every business transaction affects at least two accounts. In traditional accounting, the golden rules help determine which account to debit and which to credit.
For example, when a business pays office rent, it records an expense and reduces its bank balance.
The total debits and credits must always be equal.
2. First Golden Rule: Debit the Receiver, Credit the Giver
This rule applies to personal accounts, including accounts of individuals, businesses, and organizations.
Example: ABC Trading LLC purchases goods worth AED 5,000 on credit from XYZ Suppliers.
XYZ Suppliers is credited because it is the giver of goods in the traditional classification.
When the business later pays the supplier, XYZ Suppliers is debited and Bank is credited.
This rule helps businesses understand customer receivables and supplier payables.
3. Second Golden Rule: Debit What Comes In, Credit What Goes Out
This rule applies to real accounts, which traditionally represent assets such as cash, machinery, equipment and furniture.
Example: A Dubai business purchases office furniture for AED 3,000 and pays immediately from its bank account.
Furniture is debited because an asset comes into the business.
Bank is credited because money goes out.
This is a simplified example excluding VAT and other applicable transaction adjustments.
4. Third Golden Rule: Debit Expenses and Losses, Credit Incomes and Gains
Nominal accounts record income,expenses, gains, and losses.
Example: A company pays AED 2,000 office rent.
Rent is debited because it is an expense.
Now consider the business earning AED 4,000 in service income, received in its bank account.
The Bank account is debited AED 4,000, and Service Revenue is credited AED 4,000.
5. How Do the Golden Rules Work Together?
Consider three transactions for a UAE trading business.
Each transaction follows double-entry accounting: one or more debits must equal one or more credits.
In modern accounting, asset, liability, equity, income and expense classifications provide a more comprehensive way to determine debit and credit treatment.
The traditional golden rules remain useful for beginners.
6. What Is the Difference Between Debit and Credit?
Debit and credit do not always mean money coming in or going out.
Their effect depends on the account type.
For example, receiving money from a customer increases Bank, but may also reduce Accounts Receivable rather than create new revenue.
This distinction prevents common bookkeeping errors.
7. Why Are Accounting Rules Important for UAE Businesses?
Accurate journal entries help businesses prepare profit and loss statements, balance sheets and transaction ledgers.
They also support financial records used in UAE VAT and Corporate Tax reporting.
For example, VAT collected from customers is normally recorded as a liability rather than business income.
Similarly, purchases of machinery and ordinary operating expenses may require different accounting treatment.
Understanding these differences helps businesses maintain more reliable books and supporting records.
8. How Can Vinimay Help With Double-Entry Bookkeeping?
Vinimay offers general accounting features such as sales invoicing, purchase records, receipts, payments, customer and vendor ledgers, inventory and financial reporting.
These tools can help businesses organise transactions and reduce dependence on handwritten bookkeeping records.
However, Vinimay's UAE-specific VAT compliance, Corporate Tax calculations, IFRS reporting and EmaraTax integration have not been independently verified. Businesses should confirm these requirements separately.
Frequently Asked Questions
Related Topics
Published by prachi kahar
Our editorial and compliance specialists create practical guides, tax calculation rules, and operational strategies to empower Indian small business owners and accountants.