Who Needs Audited Financial Statements for Corporate Tax?
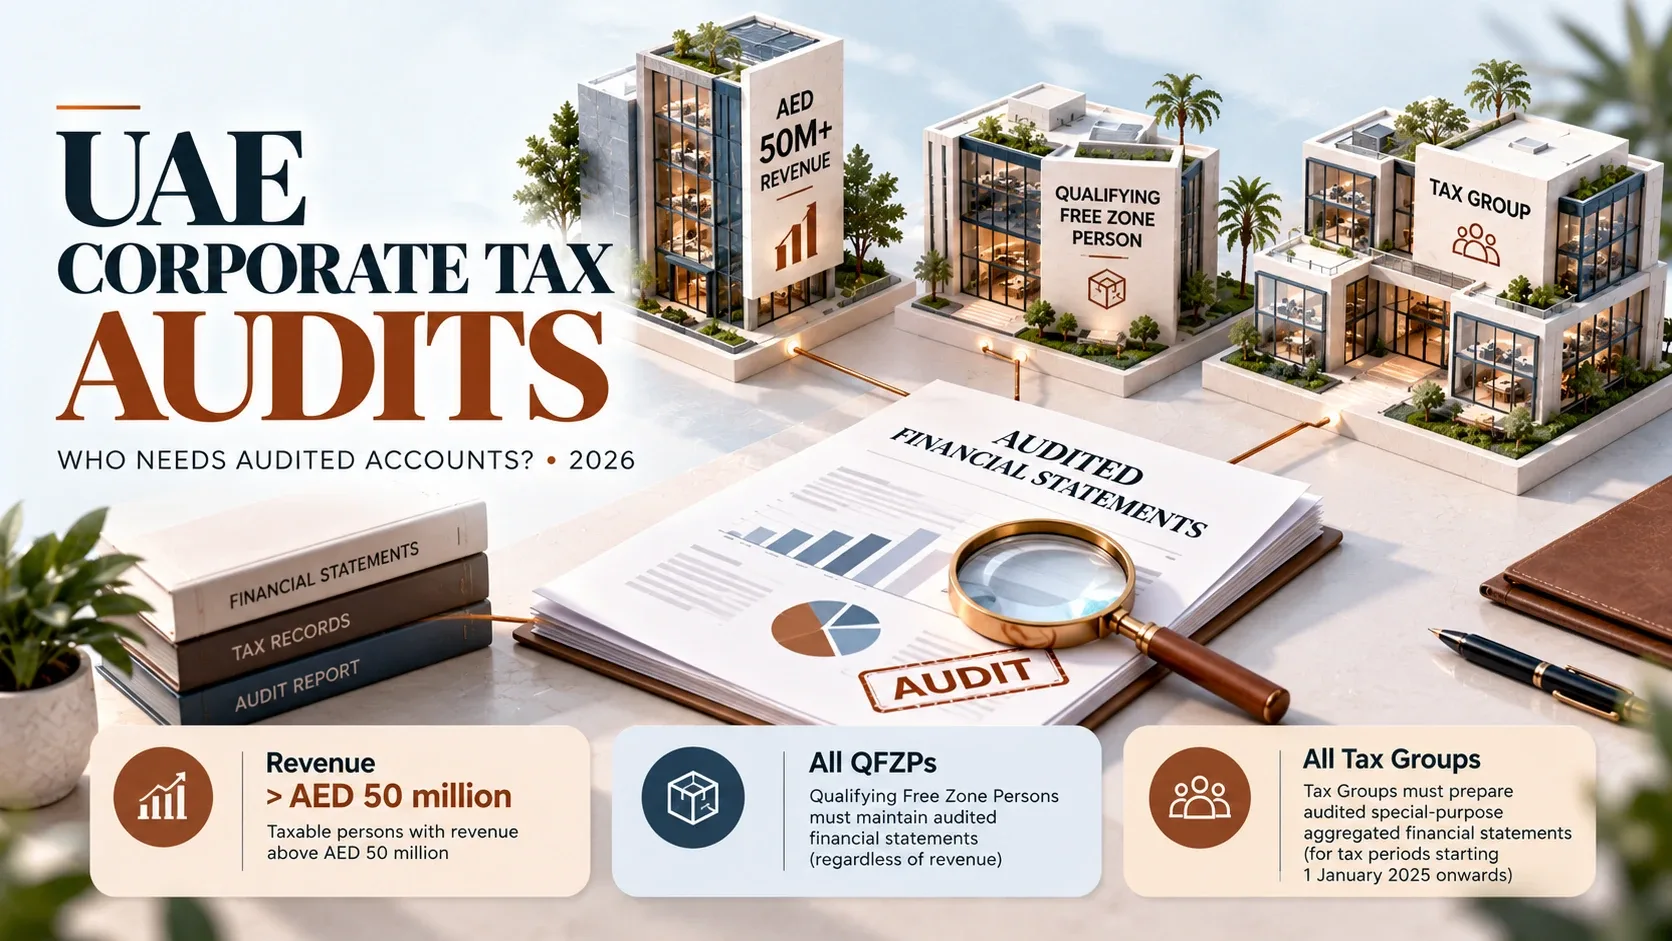
Quick Answer: Under UAE Corporate Tax rules, audited financial statements are generally required for taxable persons earning more than AED 50 million in revenue, all Qualifying Free Zone Persons (QFZPs), and Corporate Tax Groups. Tax Groups must prepare audited special-purpose aggregated financial statements. These rules apply to tax periods beginning on or after 1 January 2025.
Many businessesin Dubai, Abu Dhabi and other Emirates are unsure whether they need a statutory audit after Corporate Tax registration.
The Federal Tax Authority (FTA) and Ministry of Finance (MoF) have introduced specific audit requirements. However, Corporate Tax registration does not automatically mean every business needs audited accounts.
1. What Are Audited Financial Statements?
Audited financial statements are financial reports examined by an independent auditor.
The auditor reviews the business's accounting information and supporting evidence before expressing an opinion on whether the financial statements are fairly presented under the applicable reporting framework.
Common statements include the balance sheet, profit and loss statement, cash flow statement and accompanying notes.
These reports help support Corporate Tax calculations and improve financial reporting reliability.
2. Which UAE Businesses Must Have Audited Accounts?
Ministerial Decision No. 84 of 2025 identifies three main categories.
The requirements apply to tax periods commencing on or after 1 January 2025.
For earlier tax periods, Ministerial Decision No. 82 of 2023 continues to apply.
3. What Is the AED 50 Million Audit Threshold?
The AED 50 million threshold applies to revenue, not taxable profit.
For example:
The statutory threshold is revenue exceeding AED 50 million.
A business with substantial revenue but low profits can therefore still require audited financial statements.
For non-resident taxable persons, the relevant revenue calculation generally considers income through UAE permanent establishments or taxable nexuses.
4. Must Free Zone Companies Have Audited Financial Statements?
A qualifying free zone person must prepare and maintain audited financial statements regardless of its revenue.
For example, a QFZP earning AED 2 million in annual revenue still requires audited accounts.
However, not every Free Zone company is automatically classified as a QFZP.
A free zone business that does not have QFZP status may fall outside the corporate tax audit requirement when its revenue does not exceed AED 50 million.
Important: Individual Free Zone authorities may separately require audited accounts under licensing or regulatory rules.
5. What Are the Audit Rules for Corporate Tax Groups?
Corporate tax groups have a separate requirement.
From tax periods beginning on or after 1 January 2025, all Corporate Tax Groups must prepare audited special-purpose aggregated financial statements, regardless of group revenue.
Individual group members are not required to prepare audited standalone financial statements solely for corporate tax purposes.
The parent company should ensure that member-company accounts, intercompany balances, and required aggregation adjustments are properly documented.
The FTA has published dedicated guidance on tax group financial statements and their audit requirements.
6. When Must Audited Financial Statements Be Prepared?
The audit should be completed in time to support accurate Corporate Tax reporting.
Corporate Tax returns are generally due within nine months after the tax period ends.
Businesses should check whether their audit reports must accompany a filing or be maintained for possible FTA requests.
Corporate Tax supporting records generally must be retained for seven years after the relevant tax period.
7. What Happens if a Business Does Not Prepare Audited Accounts?
Failing to prepare required audited statements can cause corporate tax compliance problems.
For QFZPs, the audit requirement is especially important because failure to satisfy qualifying conditions may affect eligibility for the preferential 0% corporate tax treatment.
Businesses should review the applicable administrative penalties, recordkeeping obligations and tax consequences.
An audit requirement under Corporate Tax law is also separate from any audit obligation imposed by a bank, regulator, shareholder or Free Zone authority.
8. How Can Vinimay Help Businesses Prepare for Audits?
Maintaining accurate accounting records throughout the year makes audit preparation easier.
Vinimay provides general accounting features for managing:
Sales invoices and revenue records.
Purchase invoices and expenses.
Customer and supplier ledgers.
Inventory and transaction history.
Financial statements and accounting reports.
These functions can help businesses organise records and prepare information for auditors and tax advisers.
However, Vinimay's UAE-specific statutory audit reporting, IFRS compliance, Corporate Tax calculations and EmaraTax filing capabilities have not been independently verified.
Accounting software supports recordkeeping but does not replace an independent audit.
Conclusion
UAE corporate tax audit requirements depend on a business’s revenue and tax status. For tax periods starting on or after 1 January 2025, businesses that are not part of a tax group must maintain audited financial statements if their revenue exceeds AED 50 million. Every Qualifying Free Zone Person (QFZP) must also maintain audited financial statements, regardless of revenue. Tax groups must prepare audited special-purpose financial statements. Businesses should also check separate mainland and free zone authority requirements to ensure full compliance.
To simplify daily accounting, businesses can use Vinimay’s free bilingual billing software to create invoices in English and Hindi, manage sales bills, and organize transaction records. This free invoice billing software supports systematic billing and record-keeping for tax preparation.
Frequently Asked Questions
Related Topics
Published by prachi kahar
Our editorial and compliance specialists create practical guides, tax calculation rules, and operational strategies to empower Indian small business owners and accountants.